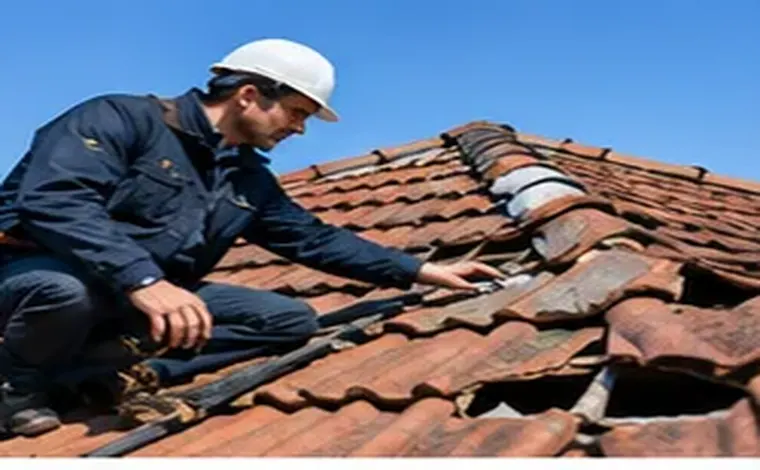
What counts as building damage in a Canadian policy
Under a homeowner or commercial property policy, the building (often called the dwelling) covers the structure and permanently attached elements: roof, walls, windows, built-in cabinetry, fixed flooring and service systems. Detached structures such as garages or sheds may sit under a separate limit.
Comprehensive policies cover all risks of direct physical loss except those excluded, while named-perils policies list the events covered. Wear and tear, gradual deterioration, settling and foundation cracking are commonly excluded, so the cause of the damage drives coverage before the amount is ever discussed.
Weather perils typical of Canada
Hail on the Prairies, windstorms in Atlantic Canada and southern Ontario, heavy snow loads and ice storms in Quebec and Ontario, and freeze-thaw cycles everywhere produce distinctive damage patterns. Ice damming, where meltwater backs up under shingles, is a classic grey zone: insurers sometimes argue it reflects poor maintenance or ventilation rather than a sudden event. Clear evidence of timing and weather conditions helps.
Where repair estimates tend to diverge
The insurer's adjuster usually prepares or reviews an estimate built with standard estimating software. Common sources of disagreement are partial versus full roof replacement, whether hail bruising has damaged shingles even without visible holes, repair versus replacement of siding, and the quantity of drywall, insulation or framing affected.
An independent adjuster will often bring in a roofer or engineer, document damage with close-up photographs, test squares or drone imagery, and produce a line-by-line counter-estimate so the negotiation is about specific items rather than a global figure.
Where the insurer relies on a desk review of photos, ask for a physical reinspection. Hidden damage such as lifted shingles, cracked rafters or wet insulation is easy to miss on images taken from the ground.
- Measurements of each roof slope and elevation
- Photos with scale references and dates
- Manufacturer data for discontinued materials
- Local weather reports for the date of loss
Matching and discontinued materials
When only part of a roof or wall is damaged and the original material is no longer available, the question is whether the insurer must pay to replace undamaged sections so that the building has a uniform appearance. Policy wording and provincial case law vary, and there is no single Canadian answer. A well-documented search for matching products strengthens your request.
By-law and building code upgrades
Repairs must meet current codes, which can be stricter than when the building was built: electrical upgrades, insulation, structural reinforcement or accessibility. Many policies limit or exclude the extra cost unless a by-law endorsement has been purchased. Check this cover before demolition starts, and obtain written confirmation from the municipality where an upgrade is mandatory.
Step-by-step: from notice to settlement
Report the loss quickly, take reasonable steps to protect the building, and keep invoices for tarps, board-up or emergency repairs. The insurer's adjuster inspects, then issues an estimate or settlement proposal. You may be asked for a sworn proof of loss. Replacement cost policies commonly pay depreciated value first and the remainder after repairs are completed within the period stated in the policy.
If you hire a public adjuster, they usually take over communication, attend reinspections and present the counter-estimate. Keep copies of everything yourself as well.
Keep a log of every contact with the insurer, including dates, names and what was agreed. Reinspections, revised estimates and supplementary claims for hidden damage discovered during repairs are common on building files, and a clear chronology helps when a supplement is questioned.
Condominiums and shared buildings
In a condominium, the corporation's policy generally insures the common elements and the units as originally built, while the unit owner's policy covers improvements, contents and the owner's share of deductibles that the corporation may charge back. Determining which policy pays for which element is a frequent source of delay, and the corporation's declaration and by-laws matter as much as the insurance wording.
If agreement cannot be reached
For pure valuation disputes, the appraisal process in the statutory conditions of most provincial insurance acts lets each party appoint an appraiser, with an umpire to break ties. Coverage refusals go through the insurer's complaints process, then the General Insurance OmbudService outside Quebec, or the Autorité des marchés financiers in Quebec, and ultimately the courts. Note the limitation period that applies in your province.
Organisations offering this service
- Autorité des marchés financiers (AMF): Quebec financial regulator that oversees claims adjuster certification and publishes the forms and competency profiles governing the profession.
- Chambre de l'assurance de dommages (ChAD): Quebec body overseeing the damage insurance profession, including claims adjusters, which publishes annual reports on its supervisory activities.
- OmbudService for Life & Health Insurance (OLHI): Independent alternative dispute resolution service for Canadian life and health insurance consumers who are in a disagreement with their insurer.
- La Médiation de l'Assurance: Mediation service for the French insurance sector, publishing a mediator charter and an annual activity report on its handling of disputes.
External links provided for information only; check the terms directly with each organisation.
Frequently asked questions
My insurer offers to repair only the damaged shingles. Can I ask for a full roof?
You can ask, and evidence of widespread damage or the impossibility of matching materials supports your request. The outcome depends on the policy wording and the facts.
Is foundation cracking covered?
Usually not when it results from settling or gradual movement. It may be covered if caused by an insured sudden event, depending on the policy.
Do I have to use the insurer's contractor?
In general you can choose your own. If you use the insurer's network, ask who guarantees the work.
What if more damage is found once repairs start?
Notify the insurer before covering it up, with photos and a contractor's description. Supplementary claims for hidden damage are common and are normally assessed on the same basis as the original loss.
Building damage claims are won on the detail of the repair scope and the cause of loss. For what professional help costs, see the Canadian building damage fee guide on expertdassure.com.